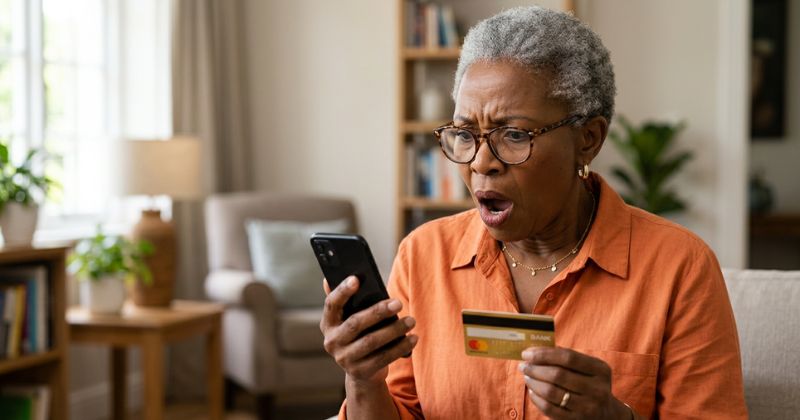
South Africans are increasingly being left to deal with debts connected to credit transactions that they say they never made or gave permission for, with fraud-related complaints lodged with the National Financial Ombud Scheme South Africa (NFO) climbing sharply in recent times.
Key Takeaways
- Fraud spans more than banking: It now hits retail, furniture, telecom and personal loan accounts, not just bank cards.
- Victim status doesn’t guarantee relief: If OTP-verified and no provider fault is found, the debt may still stand.
- Act fast, document everything: Prompt reporting and written disputes protect consumers; ignoring the issue lets debt and damage grow.
About Arcadia Finance
Get your loan sorted quickly with Arcadia Finance. No application fees, and access to 19 trusted lenders, all fully compliant with South Africa’s National Credit Regulator standards. A simple process with reliable options built around your financial needs.
The Scale of the Problem
Fraud can no longer be thought of purely as a case of money vanishing from a bank account. Criminals are more and more setting their sights on everyday credit facilities, ranging from retail and furniture store accounts to cellphone contracts and non-bank personal loans.
The NFO has reported that fraud-related complaints dealt with by its non-bank Credit Division rose by 46%, climbing from 124 cases recorded in 2025 to 181 cases in 2026, which amounts to an additional 57 cases within the space of a single year.
Nerosha Maseti, Lead Ombud for Banking and Credit at the NFO, explains that fraudsters are no longer necessarily focused on stealing the physical card itself, and are instead increasingly setting out to target the information, credentials and trust that underpin the transaction.
South Africa consistently ranks among the countries most affected by cybercrime and digital fraud on the African continent, with financial services and retail credit among the most frequently targeted sectors.
How Fraud Patterns Are Changing
According to the NFO’s case experience, fraud affecting non-bank credit can present itself in a number of different forms, including card-not-present transactions, phishing, vishing, identity theft, fraudulent personal loan applications, stolen card details and the misuse of one-time passwords (OTPs).
Consumers may also find themselves having to dispute fraud listings, whether with credit bureaux or with the Southern African Fraud Prevention Service (SAFPS).
These cases cut across retail, telecommunications and consumer credit finance, which illustrates that fraud can no longer be regarded as a problem confined solely to the banking sector.
Common Types of Credit Fraud
| Type of Fraud | Description |
|---|---|
| Card-not-present transactions | Purchases made online or telephonically without the physical card being presented |
| Phishing | Fraudulent emails or messages designed to trick consumers into revealing personal or financial information |
| Vishing | Voice-based scams, often via phone calls, where fraudsters pose as legitimate representatives |
| Identity theft | Unlawful use of a consumer’s personal details to open or access credit facilities |
| Fraudulent personal loan applications | Loans taken out in a consumer’s name without their knowledge or consent |
| Stolen card details | Card information obtained unlawfully and used for unauthorised purchases |
| OTP misuse | One-time passwords intercepted or obtained through deception and then used to authorise transactions |
Never disclose a one-time password (OTP) to anyone, even if the caller claims to be from your bank, retailer or credit provider. Legitimate institutions will never ask you to read an OTP back to them over the phone.
When Fraud Becomes a Debt Problem
The consequences of credit fraud can stretch well beyond a single unauthorised purchase.
A fraudulent transaction or credit application can lead to a steadily growing account balance, ongoing collection activity, a listing with the SAFPS, and credit information that could ultimately cause damage to a consumer’s profile.
Consumers may subsequently be left having to dispute debts, credit agreements or fraud listings connected to transactions or applications that they maintain they never authorised.
Maseti notes that the nature of credit complaints being seen by the NFO is changing. She points out that consumers are increasingly approaching the organisation not merely about account balances or the way collections are being handled, but rather about debts that have arisen from transactions they say they never authorised in the first place, something she regards as a serious consumer-protection issue.
She adds that although it is the fraudster who carries out the transaction, it is ultimately the consumer who can be left facing the debt, the collection activity, and potentially damaging credit information as a result.
When an OTP Does Not Tell the Whole Story
A Case From the NFO’s Files
One case handled by the NFO concerned a consumer who disputed an online card-not-present transaction worth R18 488.80, which had been processed on a retail store credit account on 25 March 2025.
The consumer explained that they had received a telephone call from someone claiming to be a representative of the retailer concerned. The caller warned of supposedly fraudulent activity on the account and offered assistance in preventing further fraud from taking place.
The disputed transaction was then processed shortly after this call had taken place.
The credit provider confirmed that the transaction had been authenticated by means of a one-time password that had been sent through to the consumer’s registered cellphone number, and further confirmed that no SIM swap or system compromise had been detected.
The subsequent investigation concluded that the consumer had, in all likelihood, been deceived into disclosing the OTP during what was effectively a vishing scam.
The NFO accepted that the consumer was indeed a genuine victim of fraud who had genuinely believed they were dealing with a legitimate representative of the retailer. However, it found no evidence to suggest negligence or system failure on the part of the credit provider.
Because the transaction in question had been validated using the consumer’s own security credentials, the Ombud found that there was no legal or equitable basis upon which the debt could be reversed or written off.
This case illustrates a critical point: even when a consumer is a genuine and blameless victim of fraud, this does not automatically mean the credit provider will be held liable for the resulting loss, particularly where the provider’s own security systems were not at fault and the transaction was authenticated using the consumer’s own credentials.
Do Not Ignore a Disputed Credit Transaction
The NFO is urging consumers to act without delay should they discover an unauthorised transaction appearing on a credit account.
Should the account be ignored, the outstanding balance may be allowed to grow, and this can, in turn, result in additional interest and other charges being added, ongoing collection activity, continued disputes as to whether the transaction was properly authorised, and potential consequences for the consumer’s credit report, including a possible SAFPS listing.
Maseti states that one of the worst things a consumer can do is to ignore the problem altogether, and stresses that should an unauthorised transaction appear on an account, it should be reported immediately, with a record kept of everything done to try to resolve it.
Consumers are advised to formally challenge the transaction with the relevant credit provider and to obtain a written record of the dispute, rather than simply assuming that the matter will resolve itself in due course.
Credit Providers Also Have a Role
The NFO maintains that protecting consumers should not come to an end once a transaction or account has simply been blocked. How a suspected case of fraud is dealt with after it has been reported is, it says, equally important.
Credit providers should, according to the NFO, have the following in place:
- Accessible channels through which suspected fraud can be reported;
- Prompt investigations into any transactions that are disputed;
- Proper preservation of evidence, including a record of the mitigation steps taken once the fraud has been reported;
- Clear and ongoing communication with consumers throughout the course of the investigation;
- Fair handling of collection activity while disputes are still under review; and
- Processes that take the particular circumstances of individual cases into account.
Maseti says that this is particularly important where vulnerable consumers are concerned.
She notes that a consumer who has only just discovered that their credit facility has been used fraudulently should not be expected to turn into a forensic investigator simply in order to be heard.
The NFO adds that reporting processes ought to be simple, easy to understand and responsive, while consumers, for their part, should act promptly and provide all the information available to them.
Five Steps to Take if You Suspect Credit Fraud
- Stop: Cut off all contact with the suspected fraudster immediately. Do not share any personal, banking or security information under any circumstances.
- Report: Contact your credit provider without delay, making sure to use an official telephone number or website rather than any contact details supplied by the suspected fraudster.
- Secure: Change any compromised passwords and take steps to secure affected accounts and devices.
- Dispute: Formally challenge the unauthorised transaction or credit agreement. Obtain a complaint or reference number and keep hold of all relevant evidence, including statements, SMSs, emails, screenshots and WhatsApp messages.
- Escalate: Should the complaint remain unresolved, approach the NFO, provided that the matter in question falls within its jurisdiction.
Keep a simple fraud diary noting dates, times, names of staff spoken to and reference numbers for every call or email exchanged with your credit provider. This small habit can make escalating a case to the NFO far quicker and easier.
Where Consumers Can Turn
The NFO’s services are provided free of charge to consumers. The Ombud advises that consumers should first lodge a complaint directly with their credit provider, giving that provider a genuine opportunity to resolve the matter before taking things further.
Should the dispute remain unresolved thereafter, and provided it falls within the NFO’s jurisdiction, consumers are then able to approach the NFO directly for assistance.
Conclusion
Credit fraud is no longer just about a stolen card, it’s a growing consumer-protection issue where victims can end up owing money, facing collections and carrying damaged credit records for transactions they never authorised. Acting quickly, reporting fraud through official channels, disputing transactions in writing and keeping thorough records gives consumers the best chance of a fair outcome, while credit providers, for their part, are being urged to handle these cases with clear communication, fair process and genuine regard for the circumstances of each individual consumer.
Fast, uncomplicated, and trustworthy loan comparisons
At Arcadia Finance, you can compare loan offers from multiple lenders with no obligation and free of charge. Get a clear overview of your options and choose the best deal for you.
Fill out our form today to easily compare interest rates from 19 banks and find the right loan for you.